First-Time Home Buyer in Kanata
Partner with a licensed mortgage agent serving Kanata from Ottawa and move closer to the home you've been dreaming about.
- No Hidden Fees
- 35+ Lenders
- Same Day Pre-Approval
Your Trusted Partner for a Kanata First-Time Home Buyer Loan
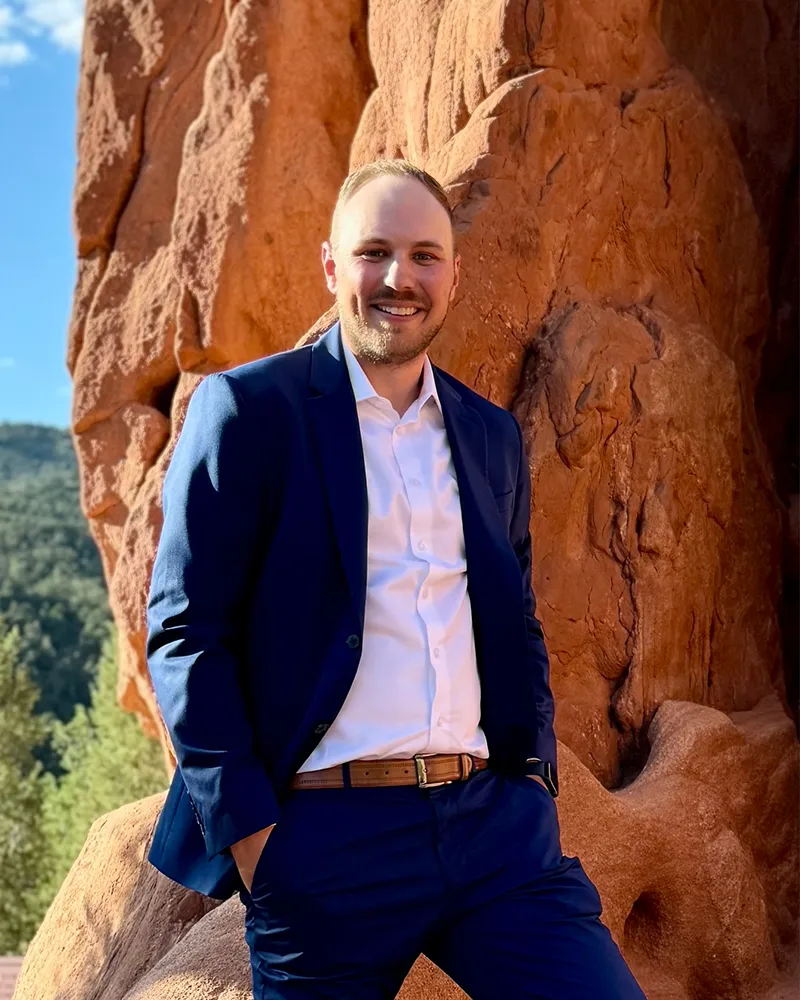
I’m Matt Price, an Ottawa-based mortgage agent committed to helping first-time home buyers purchase a home in Kanata with confidence. Rather than working for one lender, I have access to mortgage products from multiple financial institutions, allowing me to recommend solutions that work for your unique situation. Because I live and work in Ottawa, I understand the local market and neighborhood trends.
My goal is to simplify the mortgage process so you feel confident every step of the way. I’ll help you understand your options, avoid common mistakes, and choose financing that aligns with your long-term financial objectives.
Competitive Rates
Access to multiple lenders and competitive rates.
Unbiased Advice
Unbiased advice tailored to your goals.
Flexible Solutions
Flexible solutions the banks do not always offer.
Faster Approvals
A smoother and faster approval process.
Full Support
Support from application to closing and beyond.
Local Expertise
Ottawa-based agent who understands the local market.
Down Payment Programs for First-Time Buyers in Kanata
There are two government-backed programs that can make saving for your down payment easier:
First Home Savings Account (FHSA) - Government of Canada:
Save up to $8,000 per year, with a lifetime limit of $40,000, in an account that offers tax-deductible contributions. When you use the money to buy your first home, qualifying withdrawals are tax-free and don't require repayment.
Home Buyers' Plan (HBP) - Government of Canada RRSP:
Withdraw up to $60,000 from your RRSP, or as much as $120,000 for eligible couples, to put toward your home purchase. Since you're borrowing from your own retirement savings, you'll repay the amount gradually over 15 years.
Many first-time buyers use both programs together to strengthen their down payment and reduce the amount they need to borrow.
If you’re unsure which mortgage options or buyer programs are right for you, I’m here to help. With access to 35+ lenders, I’ll match you with competitive financing and a practical savings strategy for your first home in Kanata.
Estimate Your Monthly Payment
Use our calculator to estimate your mortgage payments.
What Our Clients Say
Clients choose to work with me because they value transparency, quick responses, and personalized service throughout the mortgage process. Many become repeat clients and happily refer their loved ones, knowing I’m committed to helping them make the right financial decisions.
“As first-time buyers, we were overwhelmed. Matt made everything easy and found us a rate 0.5% lower than our bank!”
Sarah & Michael T.
Barrhaven
“Refinanced and saved $300/month. Smooth process, always available. Highly recommend!”
Robert & Patricia C.
Kanata
“Self-employed, thought a mortgage was impossible. Matt found the perfect lender. Can’t thank him enough!”
Jennifer L.
Orleans
Frequently Asked Questions
Have questions? We’ve got answers.
What is the difference between a mortgage agent and a bank?
Traditional banks and credit unions can only suggest mortgages from their own bank. A mortgage agent is not bound that way. As a licensed mortgage agent in Ottawa I shop your mortgage rate and terms from over 35 lenders to find your financing that is customized to your situation.
No matter how many homes you’ve purchased in Kanata, selecting the best mortgage is an important financial decision. If someone does the comparison of lending options for you and walks you through each step, you will have more flexibility than just accepting what one bank offers you.
How much do your services cost?
For most buyers, nothing at all. The lender pays my compensation once your mortgage closes, so the rate comparisons, the application work and the support through to closing day carry no fee for you.
Alternative lending arrangements occasionally work differently. If your file is heading that way, you will know what applies well before any work starts.
How much down payment do I need?
The purchase price sets it, and the tiers run as follows:
- Under $500,000: 5% of the purchase price
- $500,000 to $1,499,999: 5% on the first $500,000, plus 10% on the portion above it
- $1.5 million and over: a minimum of 20%, since mortgage default insurance stops being available at that point
This is where Kanata differs from most of the city. Established areas like Kanata Lakes and Briarbrook carry detached prices that can approach or exceed the $1 million mark, and until recently that price point forced buyers into a full 20% down payment. The insured mortgage cap moved from $1 million to $1.5 million in December 2024, which changed the arithmetic considerably for anyone shopping at the upper end here.
A $1.1 million home now needs $85,000 rather than $220,000, because the blended 5% and 10% calculation applies rather than the flat 20%. That is not a small distinction, and plenty of Kanata buyers are still working from the old figure.
Townhomes and the newer builds toward Fernbank and Trailwest frequently sit lower, where either the straight 5% or a modest blend applies. Where you land on those tiers is worth establishing before you start viewing.
What is a mortgage pre-approval?
A pre-approval establishes what you can borrow, holds your rate for up to 120 days and tells a seller you are in a position to close. I can generally complete one within 24 to 48 hours.
A pre-qualification is the quicker, lighter version, useful when you want a monthly figure to work with rather than a firm number. Those usually take less than a day.
In Kanata the pre-approval carries extra weight during the spring market, when well-priced listings in Bridlewood and Katimavik tend to attract multiple offers. Financing conditions get scrutinised closely in that situation, and arriving with a pre-approval already in hand is often what separates a workable offer from one that gets set aside.
Can you help with bad credit or self-employment?
Yes to both, and Kanata is exactly where that question comes up most often.
Kanata North is the largest technology park in the country, and a great many buyers here are compensated in ways a standard mortgage application was never designed around. Base salary plus bonus, restricted stock units, stock options, contract engagements through a personal corporation. Lenders treat each of those differently, and some will not count certain components at all without a two-year history behind them.
That is a documentation problem rather than a qualification problem, and it is solvable. With 35+ lenders available, including alternative and non-bank options, the work is finding the lender whose policy actually fits how you are paid. Bring your last two years of T4s or Notices of Assessment, and if variable compensation forms a meaningful part of your income, bring the supporting statements too.
Credit that has taken a knock is a separate conversation, and also not disqualifying on its own.
Do I need mortgage insurance?
Yes, whenever your down payment falls under 20% of the purchase price. Default insurance protects the lender rather than you, and the premium is normally folded into the mortgage balance instead of being paid at closing.
One change worth knowing about: since December 2024, first-time buyers with an insured mortgage can amortize over 30 years rather than 25. At Kanata price points that can take a noticeable amount off the monthly payment, though it adds to the total interest across the life of the loan. Whether the trade makes sense depends on what else your budget is carrying.
I will put the premium, the payment and the total borrowing cost in front of you together so the decision is made on complete figures rather than a monthly number in isolation.
Can I use my RRSP or FHSA toward my down payment?
Yes, and most first-time buyers here should be using both. The First Home Savings Account takes up to $8,000 a year to a $40,000 lifetime maximum, contributions are tax-deductible, and qualified withdrawals for a first home come out tax-free with nothing to repay. The Home Buyers’ Plan allows up to $60,000 out of an existing RRSP, or $120,000 for an eligible couple, with no tax at withdrawal but a 15-year repayment obligation.
A couple drawing on both can assemble $200,000 between the two programs. At Kanata’s higher price points that is frequently the difference between clearing a 20% down payment and paying default insurance, which is a calculation worth running properly rather than estimating.
Ontario also refunds first-time buyers up to $4,000 of provincial land transfer tax. Ottawa charges no municipal land transfer tax on top, so a Kanata purchase carries one land transfer tax rather than the two a Toronto buyer would face. On a home in this price range the difference runs well into five figures.
Let's Make Your Next Move Simple
Whether you are exploring your options or ready to apply, I am here to help. Reach out today for a personalized mortgage strategy and discover how much you could save with a local mortgage agent in Ottawa.