First-Time Home Buyer in Barrhaven
Connect with a licensed Ottawa mortgage agent for trusted financing guidance and start your journey to a dream home in Barrhaven.
- No Hidden Fees
- 35+ Lenders
- Same Day Pre-Approval
Your Trusted Partner for an Ottawa First-Time Home Buyer Loan
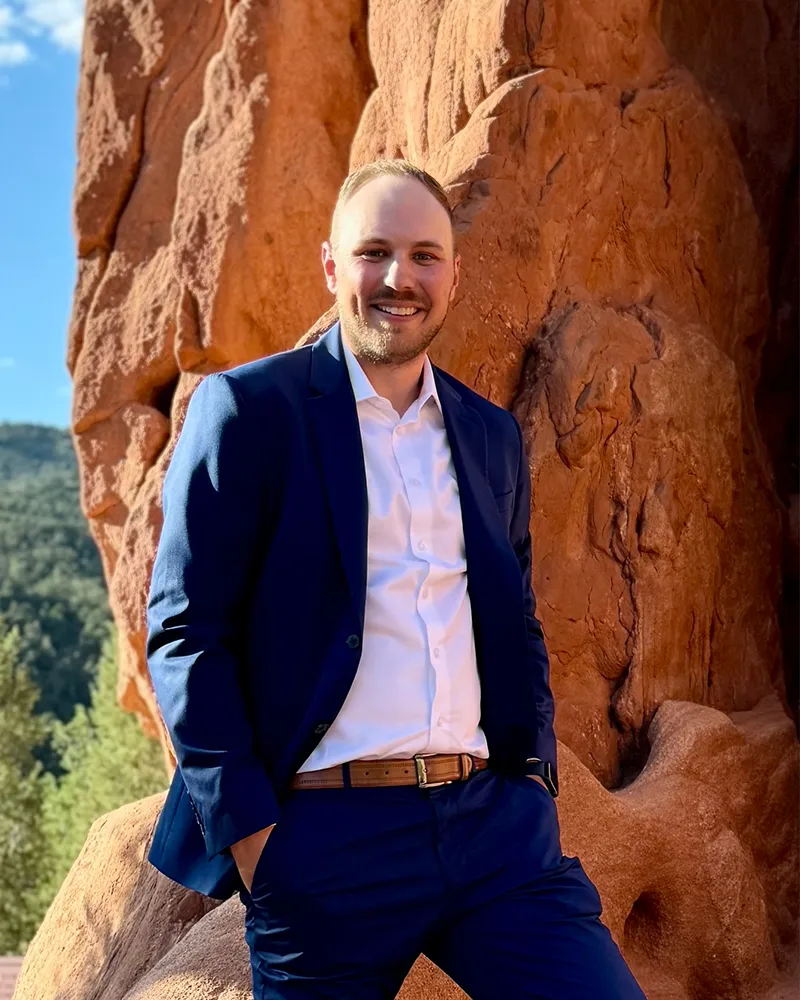
I’m Matt Price, a licensed mortgage agent based in Ottawa, helping first-time home buyers secure financing for homes in Barrhaven. Since I work independently from any single bank, I can compare mortgage options from multiple lenders to help you find the right fit. Living and working in Ottawa has given me valuable knowledge of the area’s real estate market and growing communities.
Purchasing your first home should be exciting, not overwhelming. I’ll provide honest advice, answer your questions, and help you make smart mortgage decisions that support your financial future.
Competitive Rates
Access to multiple lenders and competitive rates.
Unbiased Advice
Unbiased advice tailored to your goals.
Flexible Solutions
Flexible solutions the banks do not always offer.
Faster Approvals
A smoother and faster approval process.
Full Support
Support from application to closing and beyond.
Local Expertise
Ottawa-based agent who understands the local market.
Down Payment Programs for First-Time Buyers in Barrhaven
You may qualify for two government programs that can help grow your down payment:
First Home Savings Account (FHSA) - Government of Canada
This account allows you to contribute up to $8,000 each year, up to a lifetime maximum of $40,000, while receiving tax deductions. Qualified withdrawals for your first home are entirely tax-free, and there's no obligation to repay the money.
Home Buyers' Plan (HBP) - Government of Canada RRSP
You can withdraw up to $60,000 from your RRSP, or $120,000 if purchasing with a qualifying partner, without paying tax on the withdrawal. The amount is repaid back into your RRSP over a 15-year repayment schedule.
Many buyers maximize their purchasing power by combining both programs for the same home purchase.
Planning to buy your first home in Barrhaven but not sure where to begin? I work with more than 35 lenders to help you find mortgage solutions and savings strategies designed to make homeownership more affordable.
Estimate Your Monthly Payment
Use our calculator to estimate your mortgage payments.
What Our Clients Say
Providing honest recommendations, clear communication, and a seamless mortgage experience is always my priority. As a result, many of my clients come back for future mortgages and confidently recommend my services to friends and family.
“As first-time buyers, we were overwhelmed. Matt made everything easy and found us a rate 0.5% lower than our bank!”
Sarah & Michael T.
Barrhaven
“Refinanced and saved $300/month. Smooth process, always available. Highly recommend!”
Robert & Patricia C.
Kanata
“Self-employed, thought a mortgage was impossible. Matt found the perfect lender. Can’t thank him enough!”
Jennifer L.
Orleans
Frequently Asked Questions
Have questions? We’ve got answers.
What is the difference between a mortgage agent and a bank?
Banks and credit unions can only offer mortgages from their own organizations. As a licensed mortgage agent in Ottawa, I have access to over 35 lenders and the ability to compare a wide range of mortgage options for you, rather than pushing one lender’s products.
If you are buying a home for the first time or buying again in Barrhaven, the process can be made easier with personalized guidance. I’ll help you explore your options, so you can move forward with confidence knowing you’ve looked beyond the solution of just one lender.
How much do your services cost?
Nothing, on nearly every file. My commission comes from the lender after your mortgage funds, so the rate shopping, application, closing cost breakdown and coordination with your builder’s closing department or your lawyer cost you nothing.
If a file ever requires a lender that doesn’t pay commission, you get the fee in writing before you commit.
How much down payment do I need to buy in Barrhaven?
Barrhaven houses have been averaging around $760,000 in sale price through 2026, which puts most of them well into the tiered band.
The minimum is 5% on the first $500,000 and 10% on anything above, up to $999,999. At $1 million and over it’s 20%. So on a $760,000 Barrhaven home you need $25,000 plus $26,000, or $51,000.
Townhomes and condos change the math substantially. Barrhaven condo values have been sitting closer to $300,000, where the flat 5% applies and the minimum down payment is around $15,000. If $51,000 is out of reach this year, a Barrhaven townhome or condo is a realistic first step rather than a consolation prize, and I can show you both sets of numbers side by side.
What is a mortgage pre-approval?
Pre-approval verifies your borrowing power, holds your rate for up to 120 days and shows sellers you’re serious. I can usually have one back to you in 24 to 48 hours, or a rough pre-qualification inside a day.
Ottawa had 4.5 months of inventory in August 2026 and Barrhaven homes have been taking roughly two months to sell and closing below list price. You’re not being rushed the way buyers were a few years ago. What the 120-day hold buys you in this market is protection: if rates rise while you’re comparing four builder models and a resale on Chapman Mills, your rate doesn’t move with them.
Can you help with bad credit or self-employment?
Yes. Barrhaven has a large federal public service population where income is straightforward, and alongside it a lot of contractors, consultants and small business owners whose income is anything but.
If you’re self-employed, incorporated, or working on term contracts, I work with 35+ lenders who assess income from business financials and bank statements rather than requiring two years of clean T4s. Credit issues don’t end the conversation either. Sometimes the solution is an alternative lender for a two-year term while you rebuild, sometimes it’s waiting six months and fixing two specific things. I’ll tell you which, honestly, including when the answer is to wait.
Do I need mortgage insurance?
If your down payment is under 20%, yes. The premium runs 2.8% to 4% of the mortgage depending on your down payment percentage, and it’s rolled into the mortgage rather than paid in cash.
Ontario charges 8% provincial sales tax on that premium, and that part is due in cash at closing. On a $760,000 Barrhaven home with the minimum $51,000 down, expect roughly $2,270. It’s one of the larger line items buyers forget, so we’ll account for it early.
Can I use my RRSP or FHSA toward my down payment?
Yes, and at Barrhaven price points you’ll likely want both. The FHSA takes $8,000 a year to a $40,000 lifetime maximum, contributions are tax deductible and qualifying first-home withdrawals are tax free with nothing to repay. The Home Buyers’ Plan allows up to $60,000 from your RRSP, or $120,000 for a qualifying couple, repaid over 15 years.
A couple who has maxed both has $200,000 available. That’s well past the $51,000 minimum on an average Barrhaven house, and pushing past 20% down removes the insurance premium entirely. Whether that’s the right move depends on your rate and what else you’d do with the money, and it’s worth running the comparison rather than assuming bigger is better.
Let's Make Your Next Move Simple
Whether you are exploring your options or ready to apply, I am here to help. Reach out today for a personalized mortgage strategy and discover how much you could save with a local mortgage agent in Ottawa.