First-Time Home Buyer in Rockland
Get expert guidance from a licensed mortgage agent based in Ottawa and make your dream home in Rockland a reality.
- No Hidden Fees
- 35+ Lenders
- Same Day Pre-Approval
Your Trusted Partner for an Ottawa First-Time Home Buyer Loan
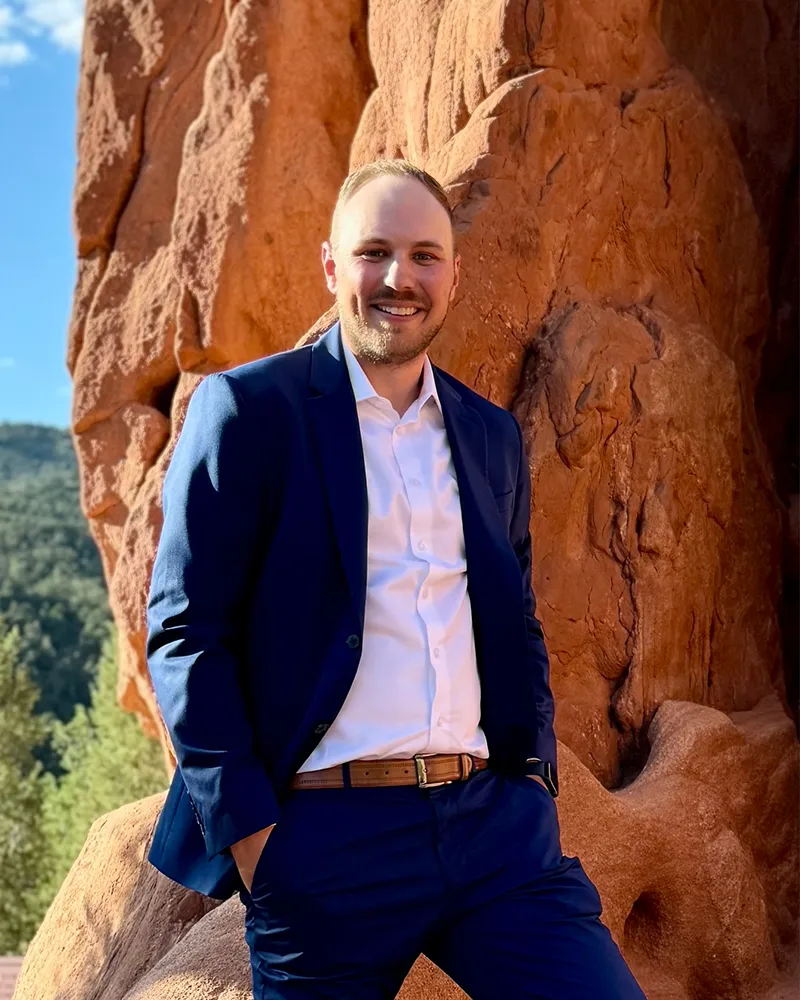
I’m Matt Price, a mortgage agent based in Ottawa, dedicated to helping first-time buyers purchase their dream home in Rockland. Unlike traditional bank representatives, I work on your behalf by searching for mortgage solutions from a variety of lenders. My experience in the Ottawa region allows me to provide insight into the local market and surrounding communities.
Whether you’re just beginning your home search or preparing to make an offer, I’ll provide the guidance you need to make informed decisions. Together, we’ll find a mortgage solution that fits both your current needs and your plans for the future.
Competitive Rates
Access to multiple lenders and competitive rates.
Unbiased Advice
Unbiased advice tailored to your goals.
Flexible Solutions
Flexible solutions the banks do not always offer.
Faster Approvals
A smoother and faster approval process.
Full Support
Support from application to closing and beyond.
Local Expertise
Ottawa-based agent who understands the local market.
Down Payment Programs for First-Time Buyers in Rockland
Two government programs are available to help increase your down payment:
First Home Savings Account (FHSA) - Government of Canada:
You can contribute up to $8,000 annually, to a lifetime maximum of $40,000, while receiving valuable tax deductions. Eligible withdrawals used to purchase your first home are completely tax-free, and you never have to repay the funds.
Home Buyers' Plan (HBP) - Government of Canada RRSP:
This program lets you withdraw up to $60,000 from your RRSP, or up to $120,000 as a couple, without immediate tax consequences. The amount withdrawn must be repaid to your RRSP over a period of 15 years.
Many home buyers take advantage of both programs at the same time to maximize the funds available for their first home purchase.
Buying your first home in Rockland starts with choosing the right mortgage. With access to over 35 lenders, I can help you compare financing options, identify available programs, and create a savings plan that supports your homeownership goals.
Estimate Your Monthly Payment
Use our calculator to estimate your mortgage payments.
What Our Clients Say
I believe every client deserves honest advice, responsive service, and support from start to finish. That’s why many of my clients return for future financing needs and recommend me to friends and family who are looking for trusted mortgage guidance.
“As first-time buyers, we were overwhelmed. Matt made everything easy and found us a rate 0.5% lower than our bank!”
Sarah & Michael T.
Barrhaven
“Refinanced and saved $300/month. Smooth process, always available. Highly recommend!”
Robert & Patricia C.
Kanata
“Self-employed, thought a mortgage was impossible. Matt found the perfect lender. Can’t thank him enough!”
Jennifer L.
Orleans
Frequently Asked Questions
Have questions? We’ve got answers.
What is the difference between a mortgage agent and a bank?
If you go into a bank or credit union, you only see the mortgage products they offer. By working with a mortgage agent, you gain access to a much broader range of financing solutions. I am a licensed mortgage agent in Ottawa and shop 35+ lenders for rates, terms and mortgage products, always putting your best interests first.
Whether you are a first time home buyer or seasoned homeowner in Rockland, you deserve to have an advocate for you during the financing process. You will get recommendations that are personalized to your financial goals, rather than just using the products of a single institution.
How much do your services cost?
Most buyers pay nothing out of pocket. My compensation comes from the lender once the mortgage closes, which means the advice, the rate comparisons, the application support and the help through closing arrive at no cost to you.
Some alternative lending files are structured differently. If yours is one, that gets raised at the outset and never after the fact.
How much down payment do I need?
It follows the purchase price, on these tiers:
- Under $500,000: 5% of the purchase price
- $500,000 to $1,499,999: 5% on the first $500,000, plus 10% on the balance
- $1.5 million or more: at least 20%, because default insurance is not offered above that price
Rockland sits in a useful position here. Prices in Clarence-Rockland generally run below what the equivalent home commands inside Ottawa, and a good share of the market falls under the $500,000 threshold where the straight 5% applies. On a $450,000 home that is $22,500 rather than the blended figure an Ottawa buyer would be calculating at the same square footage.
That gap is the main reason buyers look east along the 174 in the first place, and it is worth quantifying properly rather than assuming.
Rural properties outside the built-up area can shift the picture. Some lenders apply their own minimums on acreage, private roads or properties without municipal services, which occasionally means a larger down payment than the federal tiers alone would suggest. Worth checking before you fall for a listing.
What is a mortgage pre-approval?
Pre-approval sets your borrowing limit, locks the rate for up to 120 days and demonstrates to a seller that your financing is not speculative. Turnaround is usually 24 to 48 hours.
A pre-qualification gives you a rough monthly figure without the full application, generally inside a day.
One point specific to buying outside Ottawa: if the property you are considering is on a well and septic system, the lender will want a potability test and often a septic inspection before final approval. Those take time to arrange and can push against a tight financing condition. Raising it at the pre-approval stage rather than after an accepted offer keeps the timeline manageable.
Can you help with bad credit or self-employment?
Yes. Neither credit trouble nor self-employment closes the door, and both are common enough here that they are routine rather than exceptional.
Clarence-Rockland has a strong base of trades, contractors and small business owners, and that income is assessed differently from a salaried position. Two years of filed returns is the standard ask, though certain lenders will work from business documentation where the returns do not tell the whole story. Access to 35+ lenders, including alternative and non-bank options, usually means there is a route.
I work in both English and French, which matters in a community where a good proportion of households do their financial thinking in French even where the paperwork arrives in English.
Do I need mortgage insurance?
Yes, where your down payment comes in under 20% of the price. The insurance covers the lender if the mortgage defaults, and the premium is usually added to the mortgage balance rather than paid up front.
Since December 2024, first-time buyers with an insured mortgage have been able to amortize over 30 years instead of 25. The monthly payment drops, the total interest rises, and which of those matters more depends on your situation rather than on a general rule.
There is a rural wrinkle too. A handful of insurers and lenders apply additional conditions to properties on private services or larger parcels, and occasionally an insured mortgage is harder to place on a rural property than on an equivalent one in town. Knowing that in advance changes what you look at.
Can I use my RRSP or FHSA toward my down payment?
Yes, and using both together is the norm. The First Home Savings Account allows $8,000 a year up to a $40,000 lifetime limit, with tax-deductible contributions and tax-free qualified withdrawals that never need repaying. The Home Buyers’ Plan permits up to $60,000 from an existing RRSP, or $120,000 between an eligible couple, tax-free at withdrawal but repayable to the RRSP over 15 years.
At Rockland price points those programs go a long way. A couple who have filled both can often clear a 20% down payment outright, which removes default insurance from the equation altogether and takes the premium off the mortgage balance.
Ontario’s first-time buyer land transfer tax refund is worth up to $4,000, and at this end of the market it frequently wipes out the provincial land transfer tax completely rather than merely reducing it. Clarence-Rockland charges no municipal land transfer tax either. Do bear in mind that property tax rates here are set by Clarence-Rockland rather than the City of Ottawa, so budget from the actual figure for the property rather than an Ottawa comparison.
Let's Make Your Next Move Simple
Whether you are exploring your options or ready to apply, I am here to help. Reach out today for a personalized mortgage strategy and discover how much you could save with a local mortgage agent in Ottawa.