First-Time Home Buyer in Cornwall
Buy your dream home in Cornwall with personalized support from a licensed mortgage agent proudly based in Ottawa.
- No Hidden Fees
- 35+ Lenders
- Same Day Pre-Approval
Your Trusted Partner for an Ottawa First-Time Home Buyer Loan
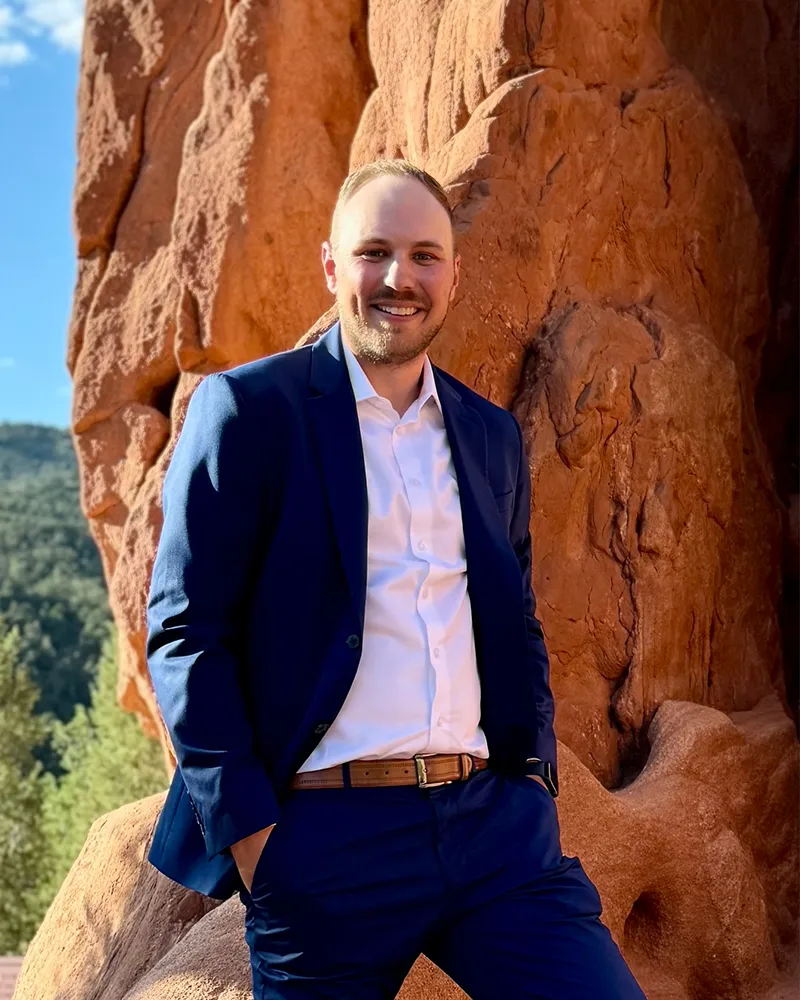
I’m Matt Price, an Ottawa mortgage agent helping first-time buyers get into homeownership in Cornwall. Rather than the products of just one financial institution, I shop mortgage options from a wide network of lenders to find financing that works for you. Serving clients all over the Ottawa area has given me a great insight into the local housing market.
I’m here to help make the mortgage process easier from start to finish, from your pre-approval to your closing day. My focus is to help you make informed decisions that fit your budget and position you for long-term financial success.
Competitive Rates
Access to multiple lenders and competitive rates.
Unbiased Advice
Unbiased advice tailored to your goals.
Flexible Solutions
Flexible solutions the banks do not always offer.
Faster Approvals
A smoother and faster approval process.
Full Support
Support from application to closing and beyond.
Local Expertise
Ottawa-based agent who understands the local market.
Down Payment Programs for First-Time Buyers in Cornwall
If you're saving for your first home, these two government programs can help increase your down payment:
First Home Savings Account (FHSA) - Government of Canada
Contribute to a tax-advantaged savings account (up to $8,000 annually and $40,000 in your lifetime). If you use it for an eligible first home purchase, the withdrawals are tax-free and you don't have to pay them back.
Home Buyers' Plan (HBP) - Government of Canada RRSP
You can withdraw up to $60,000 from your RRSP (or up to $120,000 for couples) towards the purchase of your home and not pay tax on the withdrawal. You'll repay those dollars to your RRSP over the next 15 years.
Many first-time buyers choose to use both programs in combination, which allows them to put more money down on their home purchase.
Mortgage programs can be scary to navigate, especially if you’re a first-time buyer. I have access to over 35 lenders and will help you get the right financing and build a savings strategy to make your first home in Cornwall a reality.
Estimate Your Monthly Payment
Use our calculator to estimate your mortgage payments.
What Our Clients Say
My goal is to deliver reliable advice, timely communication, and a stress-free mortgage journey from beginning to end. Many clients return whenever they need financing again and refer the people they care about because they trust me to look after their best interests.
“As first-time buyers, we were overwhelmed. Matt made everything easy and found us a rate 0.5% lower than our bank!”
Sarah & Michael T.
Barrhaven
“Refinanced and saved $300/month. Smooth process, always available. Highly recommend!”
Robert & Patricia C.
Kanata
“Self-employed, thought a mortgage was impossible. Matt found the perfect lender. Can’t thank him enough!”
Jennifer L.
Orleans
Frequently Asked Questions
Have questions? We’ve got answers.
What is the difference between a mortgage agent and a bank?
A bank or credit union can only lend its own pool of money for mortgages. When you work with a licensed mortgage agent, you have access to a broader range of financing options. I shop mortgage rates and terms from over 35 lenders to find the right fit for your financial situation from my Ottawa office.
Buying a home in Cornwall is one of life’s biggest investments, regardless of whether it’s your first purchase or your fifth. Having someone who can compare multiple lenders and explain your options helps you make a more informed decision than simply accepting a single mortgage offer.
How much do your services cost?
Nothing in the vast majority of cases. The lender pays my commission after your mortgage closes, so the rate comparison, application, closing cost planning and coordination with your lawyer come at no charge to you.
On the rare file that needs a lender who doesn’t pay commission, you’ll know the fee in writing before you agree to anything.
How much down payment do I need to buy in Cornwall?
Less than almost anywhere else within two hours of Ottawa, which is the main reason people buy here.
The rules are 5% on homes under $500,000, then 5% on the first $500,000 plus 10% on the balance up to $999,999, and 20% at $1 million and above. The median list price in the City of Cornwall was $440,000 in July 2026, and $449,900 for single detached homes, so most Cornwall buyers stay in the flat 5% band.
At $440,000 the minimum down payment is $22,000. That same 5% tier in Ottawa is doing very little for you, since the average home there is well past the $500,000 line. It’s a meaningful difference in how fast a first-time buyer can get into the market.
One thing to watch: the wider CDREB region average was $553,372 in April 2026, well above the City of Cornwall figure, because the board covers SDG and the surrounding townships. If you’re shopping in Long Sault, Ingleside or the counties, budget against that higher number instead.
What is a mortgage pre-approval?
Pre-approval sets your real budget, holds a rate for up to 120 days and tells sellers you’re financed. Most come back in 24 to 48 hours. A pre-qualification, which is a rough payment estimate rather than a verified file, takes under a day.
Cornwall had 4.1 months of inventory at the end of June 2026, up from 3.2 a year earlier, and the board’s president has described sellers as motivated with buyers slower to respond. You have some room to think. The advantage of a pre-approval in a market like that isn’t speed, it’s the rate hold. If rates move up during the eight weeks you spend looking, you keep the lower one.
Can you help with bad credit or self-employment?
Yes. Cornwall’s economy runs heavily on logistics, manufacturing, trades and small owner-operated businesses, and a lot of that income doesn’t arrive as a clean T4.
If you’re self-employed and writing off aggressively, your line 15000 may not reflect what you actually earn. I work with 35+ lenders who assess self-employed income from bank statements and business financials instead. If credit is the issue, there’s a range of options from lenders who price for lower scores through to alternative financing, and sometimes the honest answer is that a few targeted months of cleanup gets you a much better rate than borrowing today would. I’ll tell you which situation you’re in rather than just submitting the file.
Do I need mortgage insurance?
If your down payment is under 20%, yes. The premium is 2.8% to 4% of the loan depending on how much you put down, and it’s added to your mortgage rather than paid up front.
What you do pay in cash is Ontario’s 8% provincial sales tax on that premium. On a $440,000 Cornwall home with 5% down, that’s roughly $1,340 due at closing. It belongs on your closing cost list.
Can I use my RRSP or FHSA toward my down payment?
Yes, and in Cornwall these programs go further than they do in most Ontario markets. The FHSA allows $8,000 a year up to $40,000 lifetime, contributions are tax deductible, and withdrawals for a first home are tax free with no repayment. The Home Buyers’ Plan lets you take up to $60,000 from your RRSP, or $120,000 for a qualifying couple, repaid over 15 years.
Here’s why that matters locally: a single buyer with a maxed FHSA has $40,000, which is roughly 9% down on a $440,000 Cornwall home. In a $900,000 market that same $40,000 isn’t even the minimum. Cornwall is one of the few places in eastern Ontario where a fully funded FHSA on its own can put you well past the required down payment and into a smaller insurance premium.
Let's Make Your Next Move Simple
Whether you are exploring your options or ready to apply, I am here to help. Reach out today for a personalized mortgage strategy and discover how much you could save with a local mortgage agent in Ottawa.