First-Time Home Buyer in Orleans
Work with a licensed Ottawa mortgage agent and take the next step toward owning your dream home in Orleans.
- No Hidden Fees
- 35+ Lenders
- Same Day Pre-Approval
Your Trusted Partner for an Orleans First-Time Home Buyer Loan
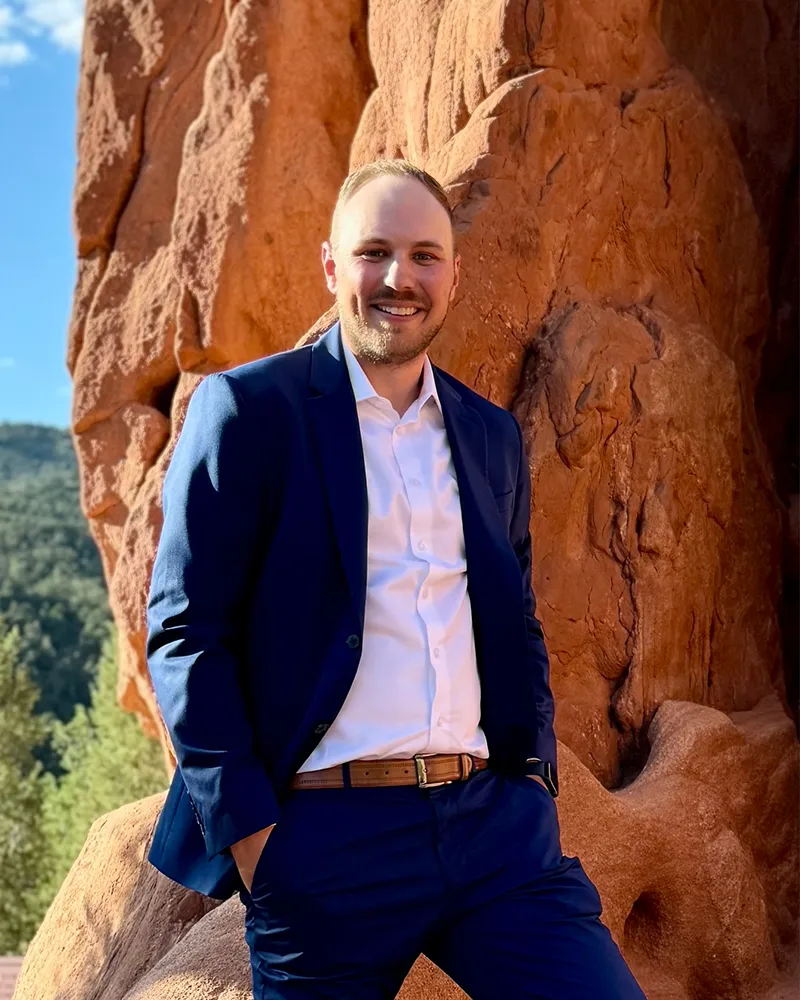
I’m Matt Price, an Ottawa-based mortgage agent helping first-time home buyers secure financing for homes in Orleans. Instead of representing a single bank, I compare mortgage options from multiple lenders so I can focus on what’s best for you. As someone who lives and works in Ottawa, I understand the local housing market and the communities that make this region a great place to call home.
Buying your first home is a major milestone, and I’m here to make the process easier. I’ll guide you through every step, explain your financing options clearly, and help you choose a mortgage that supports your long-term financial goals.
Competitive Rates
Access to multiple lenders and competitive rates.
Unbiased Advice
Unbiased advice tailored to your goals.
Flexible Solutions
Flexible solutions the banks do not always offer.
Faster Approvals
A smoother and faster approval process.
Full Support
Support from application to closing and beyond.
Local Expertise
Ottawa-based agent who understands the local market.
Down Payment Programs for First-Time Buyers in Orleans
Two government programs can help you build a stronger down payment:
First Home Savings Account (FHSA) - Government of Canada:
Contribute up to $8,000 each year, with a lifetime contribution limit of $40,000, into a tax-deductible savings account. When the money is used to purchase your first home, qualified withdrawals are completely tax-free and never have to be repaid.
Home Buyers' Plan (HBP) - Government of Canada RRSP:
Access up to $60,000 from your existing RRSP, or up to $120,000 for eligible couples, without paying tax at the time of withdrawal. Unlike an FHSA, these funds must be repaid to your RRSP over a 15-year period.
Many first-time buyers combine both programs, using savings from each to increase their down payment on the same home purchase.
Not sure which mortgage programs you’re eligible for or how to maximize your savings? With access to more than 35 lenders, I’ll help you find the right financing solution and savings strategy for your first home in Orleans.
Estimate Your Monthly Payment
Use our calculator to estimate your mortgage payments.
What Our Clients Say
My clients appreciate straightforward guidance, prompt communication, and a hassle-free mortgage experience. Many come back when it’s time to refinance or purchase another home, and they’re confident referring to friends and family because they know I’ll always put their needs first.
“As first-time buyers, we were overwhelmed. Matt made everything easy and found us a rate 0.5% lower than our bank!”
Sarah & Michael T.
Barrhaven
“Refinanced and saved $300/month. Smooth process, always available. Highly recommend!”
Robert & Patricia C.
Kanata
“Self-employed, thought a mortgage was impossible. Matt found the perfect lender. Can’t thank him enough!”
Jennifer L.
Orleans
Frequently Asked Questions
Have questions? We’ve got answers.
What is the difference between a mortgage agent and a bank?
They are limited to selling only their own mortgage products, banks and credit unions. On the other hand, a mortgage agent has access to many lenders and not just one. I am a licensed mortgage agent in Ottawa, working on your behalf shopping mortgage rates and financing options from 35+ lenders to find the best fit for your needs.
Whether you are buying your first home in Orleans or your fifth investment property, an experienced mortgage professional can help guide you through the mortgage process. Rather than taking the word of a lender, you’ll have someone working to find the best option for your individual circumstances.
How much down payment do I need?
It depends on the purchase price, and the tiers work like this:
- Under $500,000: 5% of the purchase price
- $500,000 to $1,499,999: 5% on the first $500,000, plus 10% on the portion above it
- $1.5 million or more: at least 20%, because mortgage default insurance is not available above that price
That middle tier is the one most Orleans buyers land in. A detached home here will typically carry you past the $500,000 mark, which puts you into the blended calculation rather than a flat 5%. On a $650,000 purchase, for example, that works out to $25,000 on the first $500,000 plus $15,000 on the remaining $150,000, so $40,000 rather than the $32,500 a flat 5% would suggest.
Townhomes and condos in Orleans more often sit under the $500,000 line, where the straight 5% applies. Which side of that threshold you fall on changes the number meaningfully, so it is worth pinning down early.
Not sure what you can carry comfortably once property taxes, the Orleans-side commute and everyday ownership costs are in the picture? That is what the first conversation is for.
What is a mortgage pre-approval?
A pre-approval tells you what you can realistically borrow, holds your interest rate for up to 120 days, and signals to sellers that you are a serious buyer rather than someone still exploring. I can usually turn one around in 24 to 48 hours.
A pre-qualification is the lighter version, useful when you only want a ballpark monthly figure. Those are generally done inside 24 hours.
In Orleans, the rate hold matters more than buyers expect. A good portion of the inventory here is new construction in neighbourhoods like Avalon and Cardinal Creek, and builder closing dates can sit well beyond a standard 120-day window. If you are buying pre-construction, we should talk about how the rate holds lines up with your closing date before you sign anything.
Can you help with bad credit or self-employment?
Yes, and neither situation rules you out. Credit that is less than perfect, or income that comes from self-employment rather than a T4, simply means the file needs to be placed with the right lender instead of the nearest one.
With access to 35+ lenders, including alternative and non-bank options, there is usually a workable path. Self-employed buyers should expect to show two years of filed returns or, with certain lenders, a stated-income arrangement supported by business documentation.
Ottawa’s east end has a substantial population working in federal public service alongside a strong base of small business owners and contractors. Both profiles are familiar to me, and they are underwritten quite differently.
Do I need mortgage insurance?
Yes, if your down payment is under 20% of the purchase price. Mortgage default insurance protects the lender if a borrower defaults, and the premium is usually added to your mortgage balance rather than paid at closing.
One update worth knowing: since December 2024, first-time buyers with an insured mortgage can amortize over 30 years rather than 25. Stretching the amortization lowers the monthly payment, though it increases the total interest paid across the life of the mortgage. Whether that trade is worth making depends on your budget, and it is a conversation rather than a default setting.
Before you commit either way, I will show you what the premium does to your payment and your total borrowing cost side by side.
Can I use my RRSP or FHSA toward my down payment?
Yes, and combining them is common. The First Home Savings Account lets you contribute up to $8,000 a year to a lifetime maximum of $40,000, and qualified withdrawals for a first home come out completely tax-free with nothing to repay. The Home Buyers’ Plan lets you withdraw up to $60,000 from an existing RRSP, or up to $120,000 for an eligible couple, without tax at the time of withdrawal, though that money must go back into the RRSP over 15 years.
Used together by a couple, those two programs can put a substantial down payment within reach on an Orleans purchase without either partner touching their regular savings.
There is a third piece specific to buying in Ontario. First-time buyers can claim a Land Transfer Tax refund of up to $4,000, which in practice eliminates the provincial land transfer tax entirely on homes up to roughly $368,000 and reduces it on anything above. Buying in Ottawa also means no municipal land transfer tax, unlike Toronto, so Orleans buyers face one land transfer tax rather than two. That difference is worth several thousand dollars and rarely gets mentioned until closing.
Let's Make Your Next Move Simple
Whether you are exploring your options or ready to apply, I am here to help. Reach out today for a personalized mortgage strategy and discover how much you could save with a local mortgage agent in Ottawa.