First-Time Home Buyer in Kingston
Let a licensed mortgage agent from Ottawa help you secure the right financing and achieve your dream of homeownership in Kingston.
- No Hidden Fees
- 35+ Lenders
- Same Day Pre-Approval
Your Trusted Partner for an Ottawa First-Time Home Buyer Loan
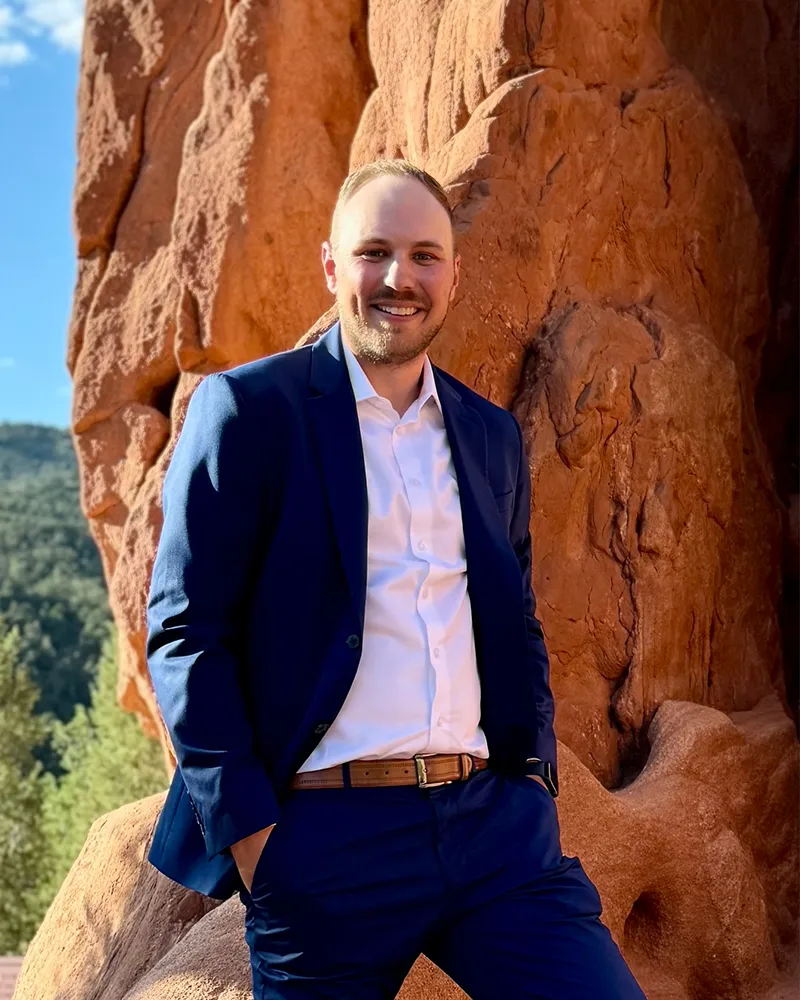
I’m Matt Price, a mortgage agent based in Ottawa, dedicated to helping first-time home buyers purchase a home in Kingston. Unlike bank-employed mortgage specialists, I work directly for my clients by comparing mortgage products from multiple lenders. My knowledge of the Ottawa area and nearby communities allows me to provide guidance tailored to today’s housing market.
As a first-time buyer, you deserve advice that’s focused on your goals. I’ll help you navigate the financing process with confidence, ensuring you choose a mortgage that supports both your homeownership dreams and your long-term financial plans.
Competitive Rates
Access to multiple lenders and competitive rates.
Unbiased Advice
Unbiased advice tailored to your goals.
Flexible Solutions
Flexible solutions the banks do not always offer.
Faster Approvals
A smoother and faster approval process.
Full Support
Support from application to closing and beyond.
Local Expertise
Ottawa-based agent who understands the local market.
Down Payment Programs for First-Time Buyers in Kingston
Two valuable government initiatives can help you save more toward your down payment:
First Home Savings Account (FHSA) - Government of Canada:
Contribute up to $8,000 per year, with a lifetime cap of $40,000, while benefiting from tax-deductible contributions. Qualified withdrawals made for your first home purchase are completely tax-free and never need to be repaid.
Home Buyers' Plan (HBP) - Government of Canada RRSP
Withdraw as much as $60,000 from your RRSP, or up to $120,000 for eligible couples, to help finance your home purchase. Because you're using your own retirement savings, the withdrawn amount must be repaid over a 15-year period.
Many home buyers combine both programs to maximize their available down payment and improve their purchasing flexibility.
Wondering which mortgage programs fit your needs or how to prepare financially for homeownership? With access to 35+ lenders, I’ll help you choose the right mortgage and develop a savings plan for your first home in Kingston.
Estimate Your Monthly Payment
Use our calculator to estimate your mortgage payments.
What Our Clients Say
Clients know they can count on me for honest guidance, responsive communication, and personalized mortgage support every step of the way. That trust has led many to return for future mortgage needs while recommending me to friends and family with confidence.
“As first-time buyers, we were overwhelmed. Matt made everything easy and found us a rate 0.5% lower than our bank!”
Sarah & Michael T.
Barrhaven
“Refinanced and saved $300/month. Smooth process, always available. Highly recommend!”
Robert & Patricia C.
Kanata
“Self-employed, thought a mortgage was impossible. Matt found the perfect lender. Can’t thank him enough!”
Jennifer L.
Orleans
Frequently Asked Questions
Have questions? We’ve got answers.
What is the difference between a mortgage agent and a bank?
Mortgage agents are not restricted to their own mortgage products as are banks and credit unions. Instead, a mortgage agent can shop for financing from a multitude of lenders. As a licensed mortgage agent in Ottawa, I work for you to shop mortgage rates, terms and products from over 35 lenders to find the best solution for your needs.
Whether you are buying your first or next Kingston property, expert guidance through the mortgage process could save you time and money. You will not be limited to the products of one lender but will have the advantage of someone whose only concern is to find the mortgage which is right for you.
How much do your services cost?
Nothing, in almost every case. The lender pays my commission once your mortgage funds, so the rate shopping, the application work, the closing cost walkthrough and the back and forth with your lawyer and realtor cost you nothing directly.
If a file ever needs a lender that doesn’t pay commission, which is rare and usually involves private financing, I tell you the fee up front and in writing before you commit to anything.
How much down payment do I need to buy in Kingston?
Kingston’s average sale price was $639,392 in April 2026 according to the Kingston and Area Real Estate Association. That puts a lot of listings just above the $500,000 line, which is where the rules change.
Under $500,000 you need 5% of the price. Between $500,000 and $999,999 it’s 5% on the first $500,000 plus 10% on everything above. At $1 million and up the minimum is 20%.
On a $639,000 Kingston home that works out to $25,000 plus $13,900, so $38,900. On a $495,000 home it’s $24,750. Ninety percent of a price difference does not translate into ninety percent of a down payment difference, and buyers are often surprised how much crossing $500,000 costs them in cash at closing. Worth knowing before you write an offer.
What is a mortgage pre-approval?
Pre-approval confirms how much you can borrow, holds your rate for up to 120 days and shows sellers you’ve done the work. I can usually turn one around in 24 to 48 hours. If you just want a payment estimate before going further, a pre-qualification takes under a day.
Kingston sat at 4.9 months of inventory in July 2026, which is a more balanced market than the region has seen in a while. You’re less likely to face a bidding war than you would have been a few years ago. That’s no reason to skip the pre-approval. A held rate protects you if rates move during your search, and it tells you your real number before you fall for a house that’s $60,000 outside it.
Can you help with bad credit or self-employment?
Yes. Kingston has a lot of buyers whose income doesn’t fit a standard pay stub: contract and term positions at Queen’s and St. Lawrence College, casual and agency work at KGH and Hotel Dieu, tradespeople running their own operations, military families posted to CFB Kingston with allowances that some lenders count and others don’t.
I work with more than 35 lenders, including alternative and non-bank options that look at bank statements and business financials rather than a T4 alone. A bruised credit score doesn’t end the conversation either. Sometimes the answer is a lender who prices for it, and sometimes it’s six months of specific cleanup first. I’ll tell you which one you’re looking at.
Do I need mortgage insurance?
If your down payment is under 20%, yes. The premium runs roughly 2.8% to 4% of the mortgage amount depending on your down payment, and it gets added to your mortgage balance rather than paid in cash. Ontario’s 8% provincial sales tax on that premium is the part you do pay at closing, and it’s the line most first-time buyers forget to budget for.
On a $639,000 Kingston home with the minimum $38,900 down, that PST cheque is roughly $1,920. I’ll give you the exact number before you commit.
Can I use my RRSP or FHSA toward my down payment?
Yes, and most Kingston first-time buyers should use both. The FHSA lets you put in $8,000 a year up to $40,000 lifetime, the contributions are tax deductible, and qualifying withdrawals for your first home come out tax free with nothing to repay. The Home Buyers’ Plan lets you pull up to $60,000 from your RRSP, or $120,000 for a qualifying couple, repaid to your RRSP over 15 years.
A couple who has maxed both has $200,000 of down payment available, which covers the minimum on a Kingston home several times over. The catch is the FHSA has to be open for a while before it’s useful, so if you’re 18 months out from buying, opening one this year is the single highest-return move available to you.
Let's Make Your Next Move Simple
Whether you are exploring your options or ready to apply, I am here to help. Reach out today for a personalized mortgage strategy and discover how much you could save with a local mortgage agent in Ottawa.